CrowdStrike (NASDAQ: CRWD) trades at approximately 188 times forward earnings, while Fortinet (NASDAQ: FTNT) and Zscaler (NASDAQ: ZS) trade around 34 and 40 times, respectively. Palo Alto Networks (NASDAQ: PANW) sits between those extremes at nearly 80 times forward earnings, a premium that climbed above 86 times after its latest earnings rally.
Table of Contents
Investors are paying heavily for Palo Alto’s growth, and Q1 FY2027 earnings gave them fresh reasons to do so. Revenue jumped 39% to $3.445 billion, while Next-Generation Security ARR surged 66% to $9.73 billion. But the quarter also exposed a much weaker GAAP operating picture and a multibillion-dollar commitment to AI infrastructure. My goal is to know whether PANW’s expansion can justify the price investors are being asked to pay.
Platformization Is Turning Cybersecurity Into A Larger Wallet Share Opportunity
Palo Alto’s valuation rests partly on its ability to capture more of the cybersecurity budget already flowing through its customer relationships. Instead of selling isolated security products, the company wants enterprises to consolidate more of their protection under its platform. That strategy gives Palo Alto multiple opportunities to expand revenue within accounts it has already won.
Q1 produced approximately 170 net new platformizations, more than 2.5 times the year-ago figure. Those customers now account for two-thirds of NGS ARR, while net retention exceeds 120%. The result is a business with more room to grow inside existing accounts, supported by recurring revenue and a broader product footprint.
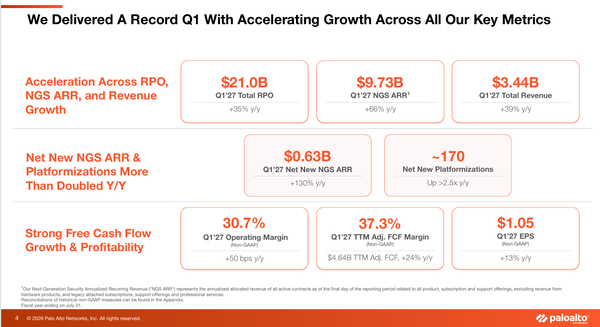
Network and AI Security revenue grew 20% to $2.282 billion, while Cortex climbed 53% to $647 million. Idira contributed $353 million following the CyberArk acquisition. Total revenue increased 39%, although acquisitions make that figure an imperfect measure of organic growth. Management raised FY2027 revenue guidance to $14.52–$14.57 billion, implying 26%–27% growth.
The AI opportunity adds another layer to this strategy. Enterprises deploying models and AI agents need to manage access, identities, data exposure, and runtime threats. Prisma AIRS generated approximately $170 million in ARR, up 45% sequentially, with more than 1,100 customers. Palo Alto is already selling into a security problem that grows as enterprise AI adoption expands.
The Premium Looks Different When GAAP Numbers Enter The Picture
A 30.7% non-GAAP operating margin gives investors a strong profitability figure to support PANW’s premium. Non-GAAP operating income reached $1.059 billion, up 50 basis points in margin year over year. GAAP operating income, however, fell from $309 million to just $96 million, leaving a margin of roughly 2.8%.
The reconciliation includes $622 million in stock-based compensation, $282 million in acquired-intangible amortization, and $55 million in acquisition-related costs. Stock compensation alone consumed approximately 18% of revenue. That is a substantial cost to shareholders through dilution, especially when the company continues to use acquisitions to expand its platform. GAAP net income of $482 million also benefited from a $457 million income tax benefit. Pretax income was only $25 million, making the reported bottom line a poor indicator of recurring profitability.
Cash generation offers a stronger part of the investment case. Operating cash flow reached $1.93 billion and free cash flow $1.84 billion, compared with $1.77 billion and $1.69 billion a year earlier. However, accounts receivable released $1.586 billion in cash during the quarter. That working-capital contribution matters when judging how repeatable the cash conversion will be. Palo Alto generates real cash, but I wouldn’t treat every dollar of this quarter’s operating cash flow as a sustainable run rate.
Applied Compute’s Impact
Palo Alto’s $4.5 billion all-stock acquisition of Applied Compute pushes the company beyond securing enterprise AI deployments and toward supplying infrastructure behind them. Applied Compute develops post-training and inference technology for open-weight AI models, allowing businesses to customize and run models while retaining control over their data and deployments.
The startup has reached approximately $100 million in annualized revenue, and management expects it to contribute $1 billion in NGS ARR by FY2029. That’s roughly tenfold growth in three years. At approximately 45 times current annualized revenue, the acquisition price assumes Palo Alto can scale the business quickly and distribute its technology across its existing customer base.
The infrastructure requirements make that ambition more complicated. Management expects cumulative capital expenditure below $3 billion through FY2030, primarily for GPUs and servers. Operating margin dilution could reach 100 basis points in FY2027 and 200 basis points in FY2028 before returning to the 29%–30% range in FY2029.
Palo Alto expects adjusted free-cash-flow margins above 38% in FY2028, excluding data-center capex. I would pay close attention to that exclusion. Servers and GPUs still consume shareholder capital even when management leaves those costs outside its preferred margin calculation. The $1 billion ARR target is promising, but investors need to see what remains after the infrastructure investment required to produce it.
86x Leaves Little Room For Disappointment
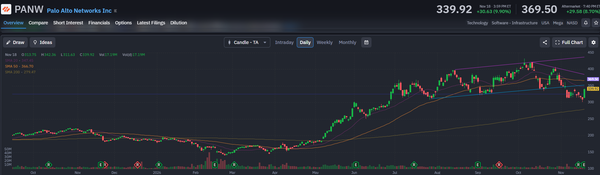
PANW closed at $339.92, up 9.9%, before reaching $369.50 after hours. The regular-session close remained below its 20-day moving average of $347.45 and 50-day average of $366.70. The after-hours rally cleared both levels, putting 366–370 in focus as the first area buyers need to defend. Above that, the 400-420 region represents the next resistance zone. The 200-day average at $279.47 remains the longer-term trend reference.
At $369.50, PANW trades at approximately 86 times the midpoint of FY2027 non-GAAP EPS guidance of $4.28. Its historical forward P/E has generally been closer to 49–57 times across recent fiscal years. The question is how much more investors should pay when GAAP operating profitability remains thin, and its newest growth initiative requires billions in infrastructure spending.
I wouldn’t chase PANW at 86 times forward earnings. I’d rather see stronger GAAP operating profitability and evidence that Applied Compute can deliver its growth targets without permanently weighing on margins and cash generation. Palo Alto is building a business worth owning. At this valuation, I’d wait for a better entry point.
Leave a Reply