EnerSys (NYSE: ENS) generated $949.9 million in second-quarter revenue, virtually unchanged from a year earlier. Yet adjusted operating earnings increased 13.7% to $152.4 million, while adjusted diluted EPS climbed 22% to $3.22.
Table of Contents
The company is finding ways to earn more from its existing sales base, even as weakness in parts of its industrial business holds back revenue growth. The segment breakdown reveals where that improvement is coming from.
Data Centers And Defense Are Carrying The Growth
PPS generated $103.8 million in revenue, up 21%, while adjusted operating earnings climbed 43.2% to $22.7 million. Its adjusted operating margin reached 21.9%, compared with 18.5% a year earlier. NIS produced $449 million in revenue, up 3.3%, but adjusted operating earnings increased 38.3% to $50.1 million as its margin expanded from 8.3% to 11.2%. Management specifically cited double-digit data-center growth.
Industrial Mobility Solutions (IMS) remains the counterweight. Revenue fell 7.8% to $397.1 million, and adjusted operating earnings dropped 13.4% to $37.5 million. Material handling is still the principal drag. Management sees early signs of recovery, but expects transportation growth to outpace higher-margin material handling next quarter, putting pressure on IMS margins.
It’s easy to see why EnerSys is gaining ground from that contrast. PPS is converting higher sales into faster earnings growth, while NIS is generating substantially more operating profit from modest revenue growth. This means the company does not need every end market to rebound simultaneously if these businesses keep expanding.
Ultralife Could Deepen The Defense Opportunity
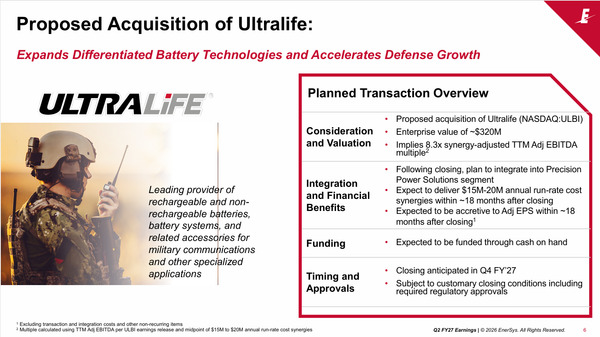
EnerSys‘ proposed acquisition of Ultralife fits the growth already emerging in PPS. Announced October 27, the transaction is intended to broaden EnerSys’ battery technologies and accelerate its position in defense markets. PPS already benefits from demand for soldier power and munitions, and Ultralife could widen the product offering and strengthen EnerSys’ ability to serve U.S. and allied military customers.
The deal remains subject to regulatory approvals and customary closing conditions, and EnerSys excluded Ultralife from Q3 guidance. And I’d treat it as potential growth, not revenue already captured.
Earnings Growth Needs To Translate Into Durable Sales
Adjusted operating earnings rose 13.7% to $152.4 million, while adjusted diluted EPS increased 22% to $3.22. However, the quarter included $44.4 million of 45X manufacturing tax credits, worth approximately $0.80 per diluted share after tax. Excluding that benefit, adjusted EPS was $2.02, still 25% above the prior-year $1.61. Gross margin improved to 29.9% from 29.1%, while the margin excluding 45X edged up to 25.2% from 24.9%. Underlying improvement is real, but headline EPS includes a substantial government incentive.
First-half cash generation improved despite a weaker quarterly comparison. Q2 operating cash flow was $142.8 million and free cash flow $130.4 million, both below the year-ago quarter, which benefited from a federal tax refund. For the first six months, operating cash flow rose to $372.8 million from $219 million, while free cash flow more than doubled to $348 million from $165.1 million. Net debt stood at $554.9 million, with leverage down to 0.8x EBITDA from 1.3x.
EnerSys returned $140.3 million to shareholders, including $130 million in buybacks and $10.3 million in dividends. For Q3, management expects revenue of $935 million to $975 million and adjusted diluted EPS of $3.05 to $3.15, including 45X credits. Data-center and defense gains must keep widening while material handling stabilizes.
ENS Stock Is Still Fighting Its Downtrend
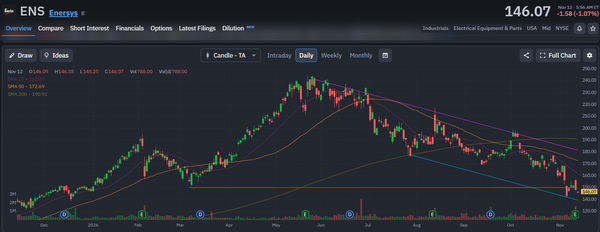
EnerSys shares have fallen to $146.07, putting them below the 20-day, 50-day and 200-day moving averages at $161.83, $172.69 and $190.91, respectively. The stock has been making lower highs since its May peak near $240, and the recent break below $150 shows sellers are still dictating the direction. The 140–145 area is now the next place to watch for buyers to step in.
A bounce from here could give ENS some much-needed relief, but I’d want to see it reclaim $150 first. The 20-day average is the next level to watch, followed by the 50-day. Getting back above those levels would give the recovery some credibility. Right now, though, ENS remains in a clear downtrend, and buyers have yet to show they can turn it around.
Added To The Watchlist
EnerSys is building a stronger earnings base through data centers and defense, with Ultralife offering another potential boost. But IMS remains weak, consolidated revenue has barely grown, and 45X credits lift adjusted EPS even as the stock remains below every major moving average.
I’d keep ENS on the watchlist rather than chase it here. The operating story is improving, but the chart has not turned and management’s near-term sales outlook does not signal a breakout in consolidated demand. A sustained move above $150 would signal buyers are returning. Until then, the downtrend deserves respect.
Leave a Reply