CoreWeave (NASDAQ: CRWV) is adding billions of dollars in quarterly sales. Yet, the cost of building and financing the infrastructure behind that growth is still swallowing a large share of the economics. The company’s third-quarter 2026 report put that tension in sharp relief.
Table of Contents
Revenue reached $3.661 billion, up 168% year over year, while diluted loss per share widened to $1.27 from $0.22 a year earlier. Investors also got a glimpse of a different phase of the business, one that could let CoreWeave earn another round of revenue from GPUs it has already deployed and financed.
A Bigger Cloud Is Producing Better Operating Leverage
CoreWeave’s revenue has climbed from $1.365 billion in Q3 2025 to $3.661 billion in Q3 2026, with the latest quarter adding more than $1 billion sequentially. That growth is backed by a $132.5 billion revenue backlog, up 138% from a year ago, with more than half attached to contracts where customer delivery is expected to begin by year-end.
The improvement is reaching the operating line as well, with GAAP operating income rising to $207 million from $52 million a year earlier and adjusted operating income climbing to $379 million from $217 million. Adjusted operating margin advanced from 1% in Q1 to 5% in Q2 and 10% in Q3, while adjusted EBITDA reached $2.256 billion at a 62% margin.
Pricing has helped push those margins higher, with management reporting increases of approximately 25% across SKUs in July and another 10% later in the quarter, followed by further increases in Q4. Short-term contracts can now command more than $40 million per megawatt annually, while new four- and five-year contracts are moving toward $20 million to $25 million per megawatt. Even older Ampere and Hopper capacity saw pricing rise 30% to 50% quarter over quarter.
The demand behind those prices is substantial, with CoreWeave reporting 1.7 gigawatts of active power and 4.6 gigawatts of contracted power at September 30, while management put qualified demand through 2027 at roughly ten times available capacity. Managed Inference has also surpassed $250 million in booked ARR, and 70% of new cloud customers added in Q3 were already Forge customers.
The Old GPU Fleet Could Deliver Another Growth Cycle
The bigger opportunity may come from infrastructure that CoreWeave has already deployed, with more than 130,000 GPUs due to come off contract in 2027 and another 170,000 in 2028. Management estimates that recontracting the 2027 fleet could generate nearly $4 billion in incremental annualized revenue, rising to almost $10 billion when the 2028 GPUs are included.
The economics could be attractive because the infrastructure will have completed its initial financing cycle, with management explaining that the delayed-draw loans funding long-term contracts are repaid by the time those contracts end. CoreWeave could then earn another round of revenue from the same GPUs without repeating the original investment in hardware and data-center construction.
The company is already collecting commitments tied to this strategy, expecting approximately $9 billion in customer prepayments and deposits over the next three months, including more than $3 billion connected to recontracting existing infrastructure that requires no additional CapEx. Management also reported that pricing for older-generation GPUs is rising, giving the installed fleet a chance to remain productive beyond its initial contracts.
Those projections still depend on CoreWeave retaining customers, keeping older GPUs competitive and securing renewals at the prices management expects. The nearly $4 billion and $10 billion figures are potential annualized revenue, not guaranteed profit or free cash flow, and operating costs will continue even after the original financing has been repaid.
The Cost Of Building This Cloud Remains Enormous
The company spent $14.5 billion on capital expenditures in Q3 and raised its FY2026 CapEx outlook to $37–$39 billion, while interest expense reached $846 million, compared with $310 million a year earlier. Management expects another $1.05 – $1.15 billion in interest expense in Q4, and GAAP net loss widened to $709 million.
Management expects customer contracts, prepayments, asset-level loans and operating cash flow to fund most of the buildout, supported by $6.5 billion in cash, restricted cash and marketable securities and nearly $5 billion in undrawn delayed-draw facilities. Full-year revenue guidance now stands at $13–$13.3 billion, with adjusted operating income of $1.27–$1.375 billion and exiting annualized run-rate revenue of $20–$21 billion.
CRWV Stock Still Has A Damaged Chart
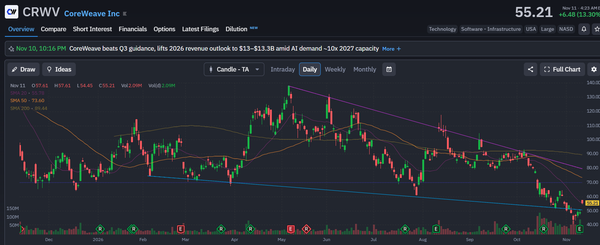
The earnings report sparked a 13.3% rally to $55.21, but the move has yet to repair the larger technical picture, with CRWV still below its 20-day moving average at $55.78, its 50-day at $73.60 and its 200-day at $89.44. The stock has also fallen beneath the marked $70 support area and remains under a descending trendline drawn from its May peak near $137.
Buyers first need to reclaim the 20-day average and hold above it, followed by a recovery through $70. The 50-day average remains a much higher hurdle, and the earnings-session jump alone does not establish a reversal of the broader downtrend.
What’s Next For CoreWeave’s Economics?
CoreWeave’s installed GPU fleet gives the company a credible route to generating another cycle of revenue from infrastructure whose original financing has been repaid. Combined with rising prices, a record backlog, and expanding operating margins, that gives me a bullish view of the underlying business. The renewal opportunity could also reduce the amount of fresh capital required to support future growth.
But I would not call CRWV stock a buy on this chart yet. The share price remains well below its major moving averages, while interest expense and capital spending continue to place a heavy burden on the business. I want to see the renewal economics appear in reported cash generation and the stock reclaim key resistance before treating the earnings rally as the start of a sustained recovery.
Leave a Reply