Verizon (NYSE: VZ) gave investors a reason to feel better about its business. The telecommunications company beat Wall Street’s third-quarter earnings expectations, raised its full-year outlook, and delivered a sharp improvement in customer growth.
Table of Contents
For investors, the appeal goes beyond one beat. Verizon needs to show it can attract customers while keeping the business profitable. Selling more service through expensive promotions can help subscriber numbers, but it does not necessarily leave shareholders better off. This quarter offered encouraging evidence that the company is making progress on both fronts. Still, a revenue miss shows there is room for improvement.
Earnings Beat Expectations, but Revenue Falls Short
Verizon reported adjusted earnings of $1.31 per share, topping analysts’ expectations of $1.27. Revenue reached $34.31 billion, below the $34.77 billion Wall Street anticipated.
That makes this a mixed report at the top line, even with the stronger profit performance. Investors should distinguish between a company earning more than expected and bringing in more sales than expected. Verizon accomplished the former. Compared with a year earlier, adjusted earnings increased 8.3%, while total revenue rose 1.5%. Equipment revenue fell 9% as customers kept phones longer and the company reduced device subsidies.
Customer Growth Provides a Bigger Surprise
The most encouraging number was Verizon’s addition of 406,000 net postpaid phone subscribers. These are customers who pay for service through a monthly bill.
Analysts expected about195,000 additions. However, Verizon brought in more than twice the number anticipated. That matters because wireless providers compete for customers who can choose among several carriers. Winning an account creates the opportunity to collect recurring payments, sell additional services, and build a longer customer relationship.
But attracting customers is only half the challenge. Keeping them without constantly offering expensive incentives is just as important. Verizon reported lower customer turnover, while its promotional costs for acquiring and retaining customers declined. Mobility and broadband service revenue increased 2.9% to $23.5 billion.
Taken together, those figures suggest the company’s improvement involves more than simply spending heavily to boost subscriber totals. The next test is consistency. A strong quarter gets investors’ attention. Repeating that performance makes a more convincing case that the business has improved.
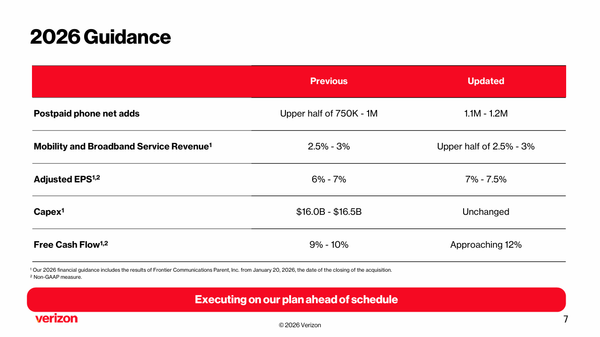
Verizon now expects full-year adjusted earnings of $5.04 to $5.06 per share, representing growth of 7% to 7.5%. Its previous forecast called for growth of 6% to 7%. Management also raised its forecast for postpaid phone net additions to between 1.1 million and 1.2 million. Free cash flow growth is expected to approach 12%, compared with the previous outlook of 9% to 10%.
An AI Opportunity Adds Interest
Verizon also announced an agreement with Amazon Web Services valued at more than $2 billion, adding another potential growth opportunity alongside its wireless business. Reuters described the agreement as an AI infrastructure deal.
The investor logic is straightforward: AI services need communications infrastructure to move information between computing systems and users. That creates opportunities beyond the companies designing chips or developing software.
Still, an announced agreement should not be treated as immediate quarterly revenue. Investors will need to watch its contribution over time. For now, Verizon’s clearest progress is in its core business. Strong subscriber additions, its earnings beat, and higher guidance provide a firmer foundation for optimism.
The next report will help show whether the company can sustain that momentum through the competitive holiday season. If customer growth continues without sacrificing profitability, investors will have a stronger reason to look beyond the initial stock-price bounce.
Can Verizon Turn Subscriber Growth Into Lasting Profits?
Verizon is giving investors more reasons to be optimistic, but the revenue miss leaves something to prove. The key now is turning new customer relationships into lasting, profitable growth while delivering on its higher earnings and cash flow forecasts. The AWS agreement adds potential, but execution in the everyday wireless business will remain essential. If Verizon can keep customers happy, control promotional spending, and strengthen sales, this quarter could mark meaningful progress toward a more durable recovery.
Leave a Reply