Palantir Technologies (NASDAQ: PLTR) heads into its November 2 earnings report with Wall Street expecting another powerful quarter. Analysts anticipate earnings will nearly double, revenue will climb more than 80%, and demand from American businesses and government customers will remain strong.
Table of Contents
That’s an impressive setup. It also leaves the AI giant with plenty to prove.
When expectations are this high, delivering strong growth may only be the starting point. Investors will want to see whether the company can outperform those forecasts and give them a reason to expect even more in the months ahead. Recent bullish calls from Rosenblatt and Citi suggest both firms believe Palantir can do just that.
What Wall Street Expects From Q3 Earnings
Palantir is expected to report third-quarter results after the market closes on Monday, November 2. The consensus is calling for adjusted earnings of $0.41 per share on revenue of approximately $2.18 billion. Compared with the year-earlier figures of $0.21 per share and $1.18 billion in revenue, those estimates imply earnings growth of roughly 95% and revenue growth of about 85%.
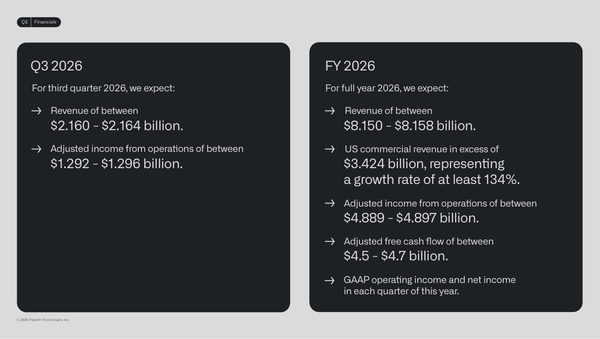
There is another useful comparison. The company previously guided for third-quarter revenue between $2.160 billion and $2.164 billion. The $2.18 billion consensus therefore already assumes the company will come in slightly above its own forecast.
Why Rosenblatt Raised Its PLTR Price Target to $260
Rosenblatt analyst John McPeake maintained a Buy rating and raised his PLTR price target to $260 from $225 ahead of the report. According to the CNBC reporting, McPeake sees continued strong growth as companies move toward using artificial intelligence across their operations. His argument is that larger deployments should help Palantir attract new customers while expanding its business with existing ones.
Winning a customer gives Palantir an initial source of revenue. Getting that customer to use its software across additional departments and business functions creates opportunities for the relationship to become much more valuable.
Commercial and Government Demand Take Center Stage
Citi analysts are also optimistic. The firm maintained its Buy rating and increased its price target to $250 from $245, pointing to encouraging discussions with Palantir’s business partners.
For the U.S. commercial business, Citi expects revenue growth above 140%, even against a much tougher year-earlier comparison. It also anticipates improving growth in the international commercial business. On the government side, Citi’s research suggests healthy demand around the federal fiscal year-end. One specialized federal partner reported growth above 60% across its broader technology practice, with Palantir identified as a major beneficiary.
That figure describes the partner’s business, rather than Palantir’s own government revenue. Still, it helps explain Citi’s confidence. The firm also cautioned against reading too much into weaker contract-tracking data, arguing that delays in reporting Defense Department awards can obscure underlying activity. Investors should remember that contract announcements and recognized revenue follow different timelines.
2026 Guidance Could Drive the Next Move in PLTR Stock
Beyond the quarterly numbers, investors should pay close attention to management’s updated forecast. Following its second-quarter results, Palantir projected full-year revenue of roughly $8.15 billion, representing about 82% growth. Citi expects another substantial increase, potentially lifting the projected annual growth rate by around 10 percentage points. That is Citi’s expectation, not guidance Palantir has issued.
Profitability will also matter. Investors should watch whether the company can support larger customer deployments while controlling expenses and generating cash. Rapid sales growth becomes more valuable when it translates into durable financial gains.
Palantir has a clear opportunity on November 2. It needs to demonstrate that demand is expanding across customers, industries, and government agencies while strengthening its outlook. The strongest report would combine its earnings beat, continued customer expansion, and guidance that supports confidence beyond a single quarter. That would give investors something more useful than AI enthusiasm.
Leave a Reply