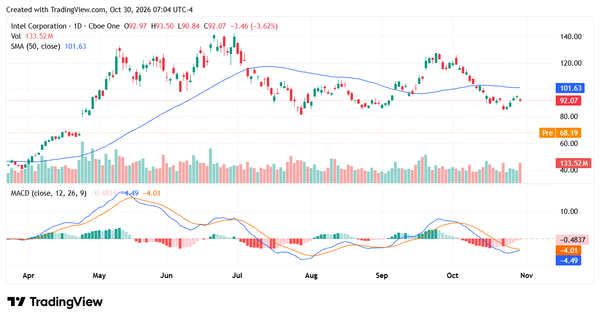
Intel (NASDAQ: INTC) isn’t looking so hot this morning. After a powerful rally fueled by optimism about artificial intelligence and its manufacturing turnaround, the chipmaker gave investors something less encouraging: a fourth-quarter forecast that fell well short of Wall Street’s expectations. Shares plunged more than 20% in extended trading Thursday as investors reassessed how quickly that recovery could deliver.
Table of Contents
BofA Securities added to the pressure, downgrading INTC to Neutral from Buy and cutting its price target to $100 from $145. The firm pointed to weakness in personal computers and insufficient progress attracting outside customers to Intel’s foundry business.
A Solid Quarter Meets a Disappointing Forecast
At first glance, Intel’s third-quarter results offered reasons for optimism.
Adjusted earnings reached 52 cents per share, beating the 40 cents analysts expected. Revenue increased 21% from a year earlier to $16.51 billion, roughly matching the $16.5 billion estimate. That represents meaningful progress. Intel is generating stronger sales, and its adjusted earnings exceeded expectations by a comfortable margin.
But investors buy shares based partly on what they expect a company to earn next. That is where Intel’s report became harder to celebrate.
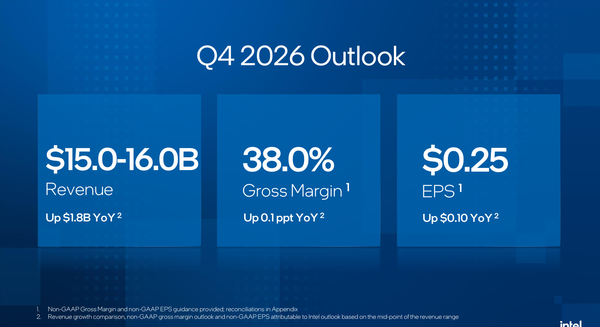
The company projected fourth-quarter revenue between $15 billion and $16 billion, with adjusted earnings of 25 cents per share. Wall Street had expected approximately $17.1 billion in revenue and earnings of 43 cents. At the midpoint, Intel’s revenue forecast is about $1.6 billion below that expectation. Its earnings outlook is roughly 42% below the consensus.
The PC Business Remains a Drag
Intel’s results show two major businesses moving in different directions.
Revenue in its client computing and physical AI group fell 5% to $8.1 billion from a year earlier. Meanwhile, data center and AI revenue climbed 78% to $7.3 billion.
Finance chief David Zinsner expects the PC slowdown to persist through at least the first half of 2027. That suggests investors may have to wait several quarters for a meaningful improvement.
BofA’s assessment adds another concern. According to the supplied report, the firm expects PC shipments to decline 25% to 30% sequentially in the fourth quarter, followed by additional inventory adjustments in early 2027.
When customers work through chips or computers already sitting in inventory, they have less reason to place new orders. That can weigh on INTC even before considering competition or manufacturing challenges.
AI Offers Growth, but Execution Matters
Intel’s data center performance remains an encouraging part of the story.
The increase in revenue suggests the company has a role in the AI spending boom. Investors often focus on graphics processors, but the company’s server processor business is also attracting demand.
Management says its immediate priority is increasing supply to meet strong demand for its Xeon processors. However, demand alone does not generate revenue. Intel also needs enough manufacturing capacity operating reliably to deliver those products.
An October explosion at its Israel manufacturing plant created another setback. The incident caused a shutdown and is expected to reduce revenue by approximately $600 million across two quarters, according to Reuters.
For shareholders, that creates a frustrating combination: weakness in one market and production constraints affecting the company’s ability to serve stronger demand elsewhere.
It also shows why improving execution remains central to Intel’s turnaround. Product demand must translate into shipments, earnings, and cash generation.
Foundry Customers Could Be the Next Big Test
Intel’s foundry strategy adds another layer of uncertainty.
A foundry manufactures chips designed by other companies. Winning that work could help Intel spread the enormous cost of its factories across a larger customer base. But the investment case requires more than advanced technology and ambitious construction plans. It requires outside customers willing to commit meaningful business.
BofA’s downgrade indicates that the firm wants stronger evidence of that progress before maintaining its previous bullish stance.
For investors, the next milestones are clear: a steadier PC business, higher server-chip shipments and credible external foundry commitments. Intel’s AI growth gives shareholders a reason to keep watching. Its weak forecast gives them a reason to demand more evidence. After a major rally, promises of future progress carry less weight when the near-term numbers move in the opposite direction.
Leave a Reply