3M Co. (NYSE: MMM) delivered another beat-and-raise quarter on Oct. 20. The 3M earnings report showed adjusted EPS of $2.50, up 12% year-over-year (YOY). That topped the consensus estimate of $2.39. Revenue of $6.6 billion landed roughly in line with forecasts.
Table of Contents
Management also raised its full-year outlook. 3M now expects 2026 adjusted EPS of $9.10 to $9.15. The prior range was $8.95 to $9.10 on a comparable basis. Shares responded, rising about 4% for the week through Tuesday’s close of $171.37.
The headline numbers were solid. But the bigger story came from a partnership announcement. 3M expanded its relationship with Amazon (NASDAQ: AMZN) around optical connectivity for data centers. The deal includes a warrant tied to $6 billion in potential sales over seven years.
That matters for how investors see this company. For years, 3M traded as a litigation story with a conglomerate attached. Today, it wants to be valued as a self-help turnaround with an AI kicker. This quarter moved that perception forward. It did not finish the job.
Here is what investors need to know about the quarter, the Amazon deal, and what still deserves caution.
Margin Expansion Did the Heavy Lifting
Adjusted organic sales grew 3.3%. That is a solid but not spectacular pace. The real strength showed up in profitability. Adjusted operating margin reached 26.2%, up 110 basis points from a year ago. Gross margin expanded by 230 basis points.
CFO Anurag Maheshwari said the margin gains included no one-time benefit. He credited cost control and productivity across the supply chain and G&A. 3M has closed 16 manufacturing sites and distribution centers so far this year. Another 10 are slated for action over the next 12 months.
Pricing also helped. CEO Bill Brown said 3M is being a bit more aggressive on price. He expects full-year pricing slightly above 1.5%, with the back half above 2%.
One accounting note deserves mention. Starting this quarter, 3M excludes intangible amortization from adjusted results. That lifts adjusted EPS by about four cents per quarter. Prior periods were restated, so YOY comparisons remain apples to apples.
Safety and Industrial Carried the Quarter
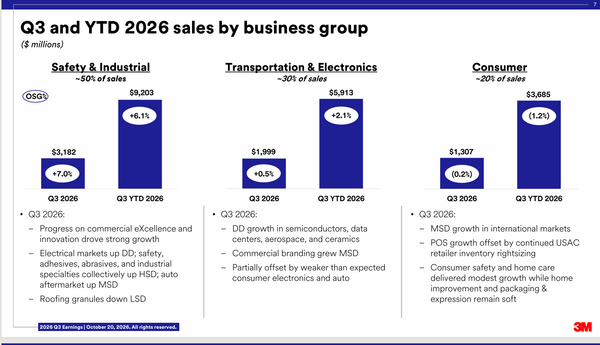
The Safety and Industrial segment was the standout. Organic sales rose 7%. Reported segment sales jumped 9.1%, helped by the Madison Fire & Rescue acquisition. Segment operating income climbed to $960 million from $792 million. Electrical Markets grew double digits on data center demand.
Transportation and Electronics grew just 0.5% organically. Consumer electronics sales fell by a mid-teens percentage. That offset gains in semiconductors and aerospace. Management pointed to a segment backlog up double digits as a reason for fourth-quarter confidence.
The Consumer segment was roughly flat, with organic sales down 0.2%. U.S. point-of-sale trends improved, but some large retailers trimmed inventory. Geographically, the U.S. and Canada grew about 7% on an adjusted organic basis. China remained the weak spot.
The Amazon Deal Changes the Conversation
The Amazon warrant covers up to 3.2 million shares, or about 0.6% of 3M’s stock. Vesting depends on $6 billion in cumulative sales of 3M optical connectivity and data center products over seven years. Brown was clear that there are no volume commitments. 3M has to earn the business.
Still, the signal matters. Hyperscalers rarely structure equity-linked deals with suppliers they doubt. 3M also announced a contract manufacturing deal with Genius Electronic Optical. It is taking a roughly 4.7% stake in that company. The goal is to scale production of its Expanded Beam Optics technology.
Here is where perception may be running ahead of fundamentals. Data center revenue should reach about $700 million this year, up from roughly $550 million. That is under 3% of total sales. Expanded Beam Optics revenue is expected near $40 million this year. The AI story is real, but it is still early.
Litigation: Off the Slides, Not Off the Books
Neither the slide deck nor the prepared remarks addressed litigation. That fits the narrative 3M wants to tell. Yet the earnings release shows the issue has not disappeared.
Net costs for significant litigation and PFAS exit were 19 cents per share, matching last year. The bigger impact was on cash. 3M made about $1 billion in pre-tax litigation and PFAS payments in the quarter. As a result, GAAP operating cash flow was just $486 million. That compares with $1.76 billion a year earlier.
Adjusted free cash flow of $1.2 billion excludes those payments. That’s a useful view of the operating business. But dividends are paid with actual cash, not adjusted cash. 3M paid about $400 million in dividends in the quarter. It also repurchased $200 million in stock.
Meanwhile, more than 15,000 PFAS personal injury cases remain pending in federal court. No new bellwether trial date has been set. No global settlement exists. Total debt also rose about $2.4 billion year-to-date, partly to fund the Madison acquisition.
This is not a red flag. It is a caution flag, mainly for income investors. The dividend yields about 1.8%. Coverage looks comfortable on adjusted numbers. It looks tighter in quarters with heavy settlement payments.
What the Chart Says
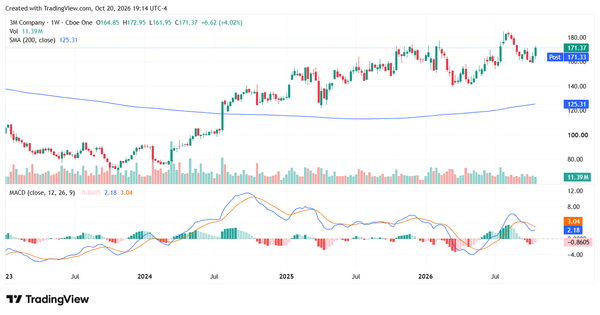
On the weekly chart, MMM remains in a long-term uptrend. Shares sit well above the rising 200-week moving average, now near $125. The stock peaked near $185 in August, then pulled back to the low $160s.
This week’s bounce is encouraging. Still, the MACD remains below its signal line. The histogram is negative but narrowing, suggesting selling momentum is fading. A weekly close above the $175 area would strengthen the bullish case. Reclaiming the August high near $185 would confirm it.
Valuation and the Bottom Line
At $171, MMM trades near 18.8 times the midpoint of 2026 EPS guidance. That is reasonable for 11% to 12% earnings growth. Management also expects 2027 organic growth near 4%. It sees margins topping its 25.4% Investor Day target.
The bull case rests on three pillars. They are steady margin gains, accelerating innovation, and a credible AI infrastructure angle. 3M launched 87 new products this quarter. It expects more than 350 for the full year.
Growth investors have new reasons to pay attention. Income investors should stay engaged but watch cash flow, not just adjusted earnings. For both groups, this quarter showed a company changing its story. The market is beginning to believe it.
Leave a Reply