All eyes will be on Nike (NYSE: NKE), which reports its Q1 fiscal year 2027 earnings report on October 1. Analysts expect another poor quarter. Investors are hoping to see some signs that its turnaround strategy is starting to help. If not, there are fears the stock could get the boot from not only the S&P 500 but also the Dow.
Table of Contents
Unfortunately, the earnings report seems more likely to support the bearish analyst sentiment. Several analysts believe the company may need more time.
Wall Street expects Nike’s revenue to decline year over year. Analysts are also bracing for weaker earnings as the company deals with softer demand, elevated costs and continued discounting.
That cautious outlook follows another challenging period for Nike. During its fiscal fourth quarter, overall revenue fell 1%, while sales in China dropped 17%. Adjusted earnings came in at 20 cents per share, beating the 13 cents analysts expected, but the better-than-expected profit was not enough to ease concerns about the company’s slow recovery.
UBS analyst Jay Sole is among those taking a cautious view ahead of the October report. Sole recently warned that Nike’s global sales trends have deteriorated over the past three months. He believes earnings could fall short of consensus expectations and that management’s fiscal second-quarter outlook may be considerably weaker than Wall Street currently anticipates.
China Remains a Major Problem
China will be one of the most closely watched parts of the report. The region accounts for roughly 15% of Nike’s annual revenue, making it the company’s third-largest market behind North America and Europe, the Middle East and Africa. Unfortunately, Nike continues to lose momentum there.
The company has struggled with weak product assortments, excessive inventory and growing competition from domestic brands such as Anta Sports and Li Ning. Chinese consumers are also becoming more selective with discretionary purchases. Management previously indicated that China’s revenue trends could remain broadly consistent with the steep declines reported last quarter as Nike and its retail partners work through excess inventory.
Investors will be looking for any sign that the decline is stabilizing. Even a smaller-than-expected drop could be viewed as progress. Another sharp deterioration, however, could raise new questions about whether Nike can regain its former strength in this important market.
Wholesale Growth Could Be a Bright Spot
One encouraging part of Nike’s recovery has been its renewed relationship with wholesale partners. Under its previous strategy, the company pulled merchandise from several retailers to sell more products directly through its own stores and websites. That decision gave competing brands more room on store shelves.
CEO Elliott Hill is now reversing much of that approach. Nike has been rebuilding relationships with retailers and restoring products to important sales channels.
Guidance Could Decide NKE’s Next Move
Nike could beat the quarter’s reduced expectations and still disappoint investors if its outlook is weak. That is why management’s forecast for the fiscal second quarter may have a greater effect on the stock than the reported earnings figure.
Wall Street will be listening for information about holiday demand, China, inventories, tariffs and the pace of new product launches. Investors should also watch management’s tone. CEO Elliott Hill has already acknowledged that Nike’s progress has been uneven and that the company is not yet performing at its full potential.
The October 1 report does not need to show a completed turnaround. That would be unrealistic. But investors do need to see credible signs that sales are stabilizing, product innovation is improving, and margin pressure is becoming manageable.
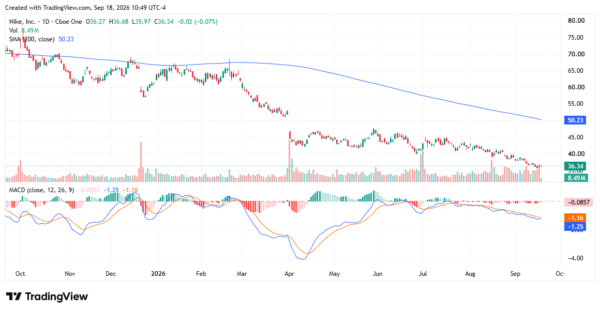
With expectations already low, even modest progress could produce a relief rally. But if Nike reports weaker earnings and issues another disappointing forecast, its stock could remain under pressure. For now, Wall Street is giving Nike very little benefit of the doubt. The October earnings report is the company’s next opportunity to show that it’s finally beginning to move forward again.
Leave a Reply