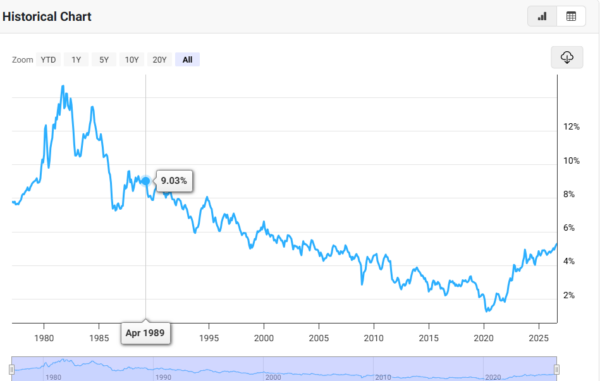
The bond market just put a new price tag on money. The U.S. 10-year Treasury briefly hit 5.041% this week, its highest level since 2007, while Germany’s 10-year Bund reached 3.572%, Japan’s 10-year government bond hit 3.036%, and Britain’s long-end yields also pushed to multi-year highs.
Table of Contents
That is a pretty big move in the benchmark that sits underneath everything from mortgages to corporate bonds. Goldman Sachs says the pressure is coming from a nasty combination of swollen government borrowing, AI-related corporate debt issuance, resilient growth and the energy shock. Governments and companies funding AI infrastructure are increasingly reaching into the same pool of global savings. And that’s the part I’m watching. The bond selloff is changing the hurdle rate for growth.
The AI Boom Has Created A Second Borrower Competing With Governments
AI infrastructure has become one of the biggest capital-spending races on the planet, and now the companies building it are showing up in the debt market at the same time governments are issuing enormous amounts of paper.
Goldman estimates nearly $500 billion of AI-related debt issuance in 2026, with hyperscalers accounting for roughly 40% of that total. Oracle (NYSE: ORCL) gives us a clean look at what this means in practice. The company said it expected to spend roughly $70 billion on AI data centers in its current fiscal year and planned to raise another $40 billion through debt and equity. Oracle shares dropped 8.9% after investors got a look at the financing requirements.
Microsoft (NASDAQ: MSFT) and Amazon (NASDAQ: AMZN) are also spending at extraordinary rates on data centers and AI infrastructure, with the major hyperscalers collectively pushing hundreds of billions of dollars into capex. Reuters reported that the five biggest hyperscalers could see capital spending exceed free cash flow by 2027. If the cost of financing rises, every one of those projects needs to clear a higher return hurdle. That is where the bond market starts showing up in the equity story.
Higher Yields Are Now Reaching The Real Economy
You don’t have to own a bond to feel the repricing.
Look at housing. The average U.S. 30-year fixed mortgage rate jumped 19 basis points in one week to 6.95%, its highest level since January 2025.
That’s the transmission mechanism in plain English – Treasury yields move, mortgage financing gets more expensive, and suddenly the same house requires a much bigger monthly payment. This is why companies like D.R. Horton (NYSE: DHI) is getting caught in the crosshairs. The homebuilder doesn’t need a housing crash for higher yields to hurt. A buyer can simply get priced out, demand can slow, incentives can rise, and projects that looked attractive under cheaper financing can become harder to justify.
The same math applies to warehouses, factories, data centers and other capital-heavy projects. Prologis (NYSE: PLD) is a useful example because even a company with strong real estate demand still has to refinance and fund an enormous asset base. These examples help us understand that higher yields don’t need to blow up the economy before investors start caring about their portfolios’ health. They only need to make the marginal project less attractive, just as we have it now.
The Market Hasn’t Reached The Scary Part Yet
Now the difference between this setup and the traditional credit scare is that credit spreads haven’t blown out. And the market isn’t panicking yet.
Goldman says the biggest tech companies have issued more than $170 billion of debt this year, while credit spreads remain near historical highs and credit volatility sits near record lows. Investors are still focused heavily on the attractive all-in yield rather than treating these borrowers as imminent credit problems. That’s actually more useful to watch.
The bond market is repricing the cost of funding before it has repriced the quality of the borrowers. And JPMorgan Chase & Co. (NYSE: JPM) is sitting right in the middle of that flow. Corporate borrowing, refinancing, underwriting and credit demand all run through the banking system, making JPM a useful name to watch as the cost of capital moves higher. The bank is also expanding its fixed-income footprint with a frontier-market local-currency bond index covering nearly $330 billion of debt across 26 countries. If companies can still borrow, the game continues. They just have to make the numbers work harder.
Watch The Cost Of Capital, Not Just The Yield
This is why I wouldn’t get hung up on whether the 10-year closes above or below 5% on any given day. The bigger signal is whether long-term yields stay elevated while the economy keeps demanding enormous amounts of capital.
I’m watching three things from here: the 10-year and 30-year Treasury yields, corporate credit spreads, and whether AI and infrastructure spending keep accelerating at a pace that can justify the financing bill.
If yields stay high but spreads remain tight, companies can keep borrowing. If yields stay high and spreads start widening, the financing squeeze gets much more serious. And if AI spending keeps climbing while free cash flow doesn’t keep pace, investors eventually have to put a higher price on the capital required to produce that growth.
That’s where the bond market can start rewriting the equity story, and by extension, millions of portfolios around the world.
Leave a Reply