
Costco Wholesale (NASDAQ: COST) will report its fourth-quarter results after the market closes on September 24, 2026. As usual, Wall Street will be watching much more than the company’s headline earnings and revenue numbers.
Table of Contents
Investors already know that the company’s stores remain busy. What they want to learn is whether the warehouse retailer can translate its impressive sales growth into stronger profits while maintaining member loyalty.
Analysts currently expect the company to report quarterly earnings of approximately $6.55 per share. However, expectations may be a little too optimistic. Bank of America is reportedly looking for adjusted earnings of $6.52 per share, while analysts at Oppenheimer have also cautioned that the consensus estimate could be difficult to beat.
That sets up an interesting earnings report. Costco’s sales appear healthy, but the company may need more than another solid quarter to satisfy investors.
COST Has Already Reported Strong Sales
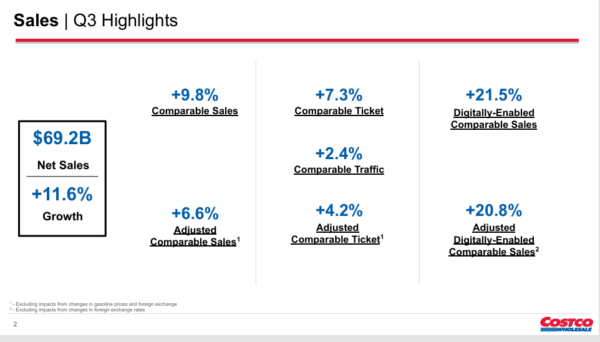
Unlike many retailers, Costco releases monthly sales updates. That means investors already have a reasonably good idea of how much merchandise moved through its warehouses during the quarter.
For the 16-week fiscal fourth quarter, Costco reported net sales of $93.9 billion, an increase of 11.3% from $84.4 billion a year earlier. Total comparable sales rose 9.4%.
Online growth was especially impressive. Digital comparable sales jumped nearly 20% during the quarter. That provides evidence that Costco is becoming more than a traditional warehouse chain. Its online operation is turning into an increasingly important growth engine.
Membership Growth Will Be Critical
Costco’s membership business is one of the most important parts of its financial model.
Membership fees provide a reliable stream of high-margin revenue, allowing Costco to keep merchandise prices low. That helps attract shoppers, strengthens customer loyalty and encourages members to renew their subscriptions.
Investors will also want to know whether more customers are upgrading to the higher-priced Executive membership.
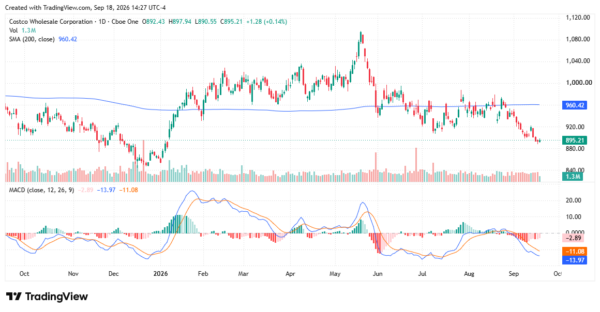
A slowdown in membership growth has become one of the market’s biggest concerns. COST stock is about 18% below its previous record despite the company’s strong sales performance.
Margins Could Decide the Market’s Reaction
Strong revenue does not automatically translate into strong earnings. That is why Costco’s operating margins may determine how investors respond to the report.
The company must manage higher wages, transportation expenses and other operating costs while maintaining the low prices that members expect. Gasoline sales can also complicate the picture. Higher fuel prices may increase reported revenue, but gasoline generally carries lower margins than many products sold inside Costco’s warehouses.
Wall Street will want to see whether Kirkland Signature, the company’s private-label brand, is helping offset those pressures. Kirkland products can provide attractive value to customers while giving Costco greater control over pricing and profitability.
Investors should also listen to the earnings call for management’s comments about tariffs, inflation and product sourcing. The company has enough purchasing power to negotiate favorable terms with suppliers, but it is not immune to rising import or commodity costs.
Could COST Announce a Special Dividend?
Some analysts believe Costco may be preparing to announce another special dividend. The company last distributed a special dividend of $15 per share in January 2024. Based on COST’s current share price and its history of returning excess cash to shareholders, that could happen.
However, there is no guarantee that management will make such an announcement alongside earnings. Still, the company’s cash-generating ability makes the possibility worth watching. A large special dividend could soften the market’s reaction if earnings come in slightly below expectations.
What to Watch After Costco Reports Earnings
Costco heads into its earnings report with strong momentum. Quarterly net sales increased by double digits, comparable sales remained healthy and digital activity expanded rapidly.
However, Wall Street already expects that. The real questions are whether profit margins are holding up, membership growth can accelerate, and management can provide a confident outlook for the new fiscal year.
Leave a Reply