Consumer staples stocks are supposed to be the safe trade when the economy wobbles. Lately, they haven’t felt that way. Many investors expect the sector to stay weak into 2027. Shoppers are trading down, volumes are flat, and pricing power has faded.
Table of Contents
There’s plenty of data to support that outlook. But it treats an entire sector as a single trade. Inside the group, some consumer staples stocks now trade under 15x earnings while their underlying businesses are improving.
A stock screener of consumer staples names highlights several of them. The five consumer staples stocks in this article share three traits:
- Each trades at a trailing price-to-earnings (P/E) ratio below 15x.
- Each carries a Buy or Moderate Buy consensus rating.
- Each has a consensus price target implying double-digit upside.
To be fair, a low valuation alone doesn’t make a stock a buy. Sometimes cheap stocks are cheap for a reason. In these five cases, however, the gap between perception and fundamentals looks wide enough to matter.
The Andersons: Record Earnings, Bigger Bets
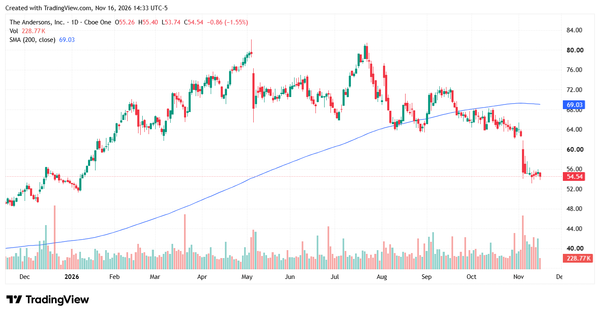
The Andersons (NASDAQ: ANDE) trades at about 9.2x trailing earnings, one of the lowest multiples among these consumer staples stocks. Its Buy rating is also the strongest in the group. The consensus price target of $95 implies roughly 73% upside from $54.85.
The fundamentals support that optimism. On Nov. 3, the agribusiness company reported record third-quarter net income of $46.4 million. Diluted EPS climbed to $1.36 from $0.59 a year earlier. Record results in the renewables segment drove the gain.
So why is the stock cheap? The company also agreed to acquire Harvestone Low Carbon Partners for $915 million. That deal adds leverage and leans further on ethanol tax credits. Investors are pricing in that risk. Management, however, still targets a $7 run-rate EPS by the end of 2028. Today’s price is less than 8x that goal.
John B. Sanfilippo & Son: A Miss That May Be Overpriced
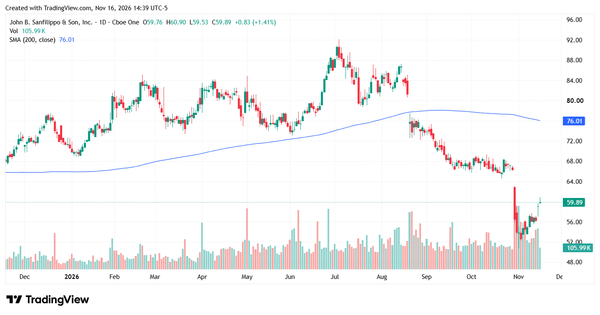
John B. Sanfilippo & Son (NASDAQ: JBSS), maker of Fisher and Orchard Valley Harvest nuts, trades at about 12.7x earnings. Analysts rate the stock a Moderate Buy. Their $100 consensus price target suggests roughly 65% upside.
The near-term news has been rough. Fiscal first-quarter EPS fell 30% to $1.11 and missed the $1.50 consensus. Lower selling prices, a weaker product mix, and lost business at some retailers weighed on profits. Protein bar shipments for a new customer were also pushed back.
Still, sales volume held steady for a third straight quarter. EPS rose more than 50% from the prior quarter, which absorbed recall-related costs. A new contract-manufacturing customer is also ramping up. Among consumer staples stocks, this selloff may reflect a bad quarter more than a broken business.
Darling Ingredients: Cash Flow Is Doing the Talking
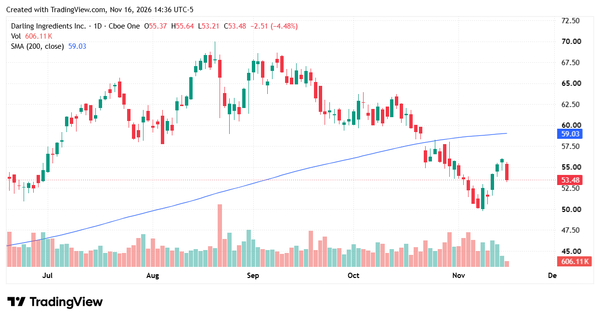
Darling Ingredients (NYSE: DAR) turns animal by-products and used cooking oil into feed, food ingredients, and renewable fuel. It trades at about 10.1x earnings. Its Moderate Buy rating comes with a $73.80 price target, or roughly 38% upside.
The third quarter was strong. Darling earned $1.67 per share, up from $0.12 a year earlier. Combined adjusted EBITDA more than doubled to $514.3 million. The quarter did include a $63.5 million gain on business sales, which flattered the bottom line.
What matters more is cash. Darling cut net debt by about $420 million and repurchased $75.9 million of stock. It also reaffirmed 2026 combined adjusted EBITDA guidance of $2.2 billion to $2.3 billion. Policy uncertainty around renewable fuels remains the key risk. Darling does not pay a dividend.
Herbalife: Growth Is Back; Margins Need to Follow
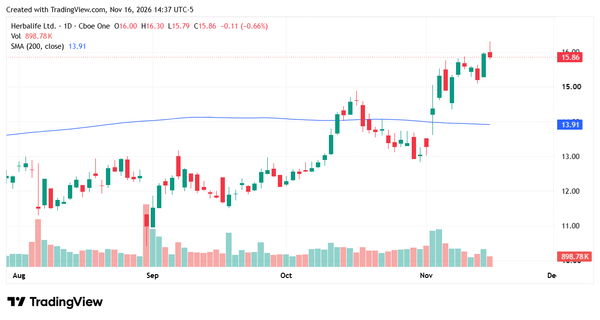
Herbalife (NYSE: HLF) trades at about 9.5x earnings. Analysts rate the nutrition company a Moderate Buy, with an $18.86 price target implying about 18% upside. That’s the smallest upside in this group. Still, the turnaround story is gaining traction.
Third-quarter net sales rose 6% to $1.35 billion. It was the company’s fifth straight quarter of year-over-year sales growth. Management raised full-year sales growth guidance for the third time, to a range of 4.9% to 5.9%.
The bottom line was weaker. Adjusted EPS of $0.64 missed the $0.73 consensus, and fourth-quarter guidance implies lower margins. The company is also operating under an interim CEO. On the plus side, net leverage fell to 2.0x, and the board authorized a $250 million buyback. If margins catch up to sales, today’s multiple looks too low.
Natural Grocers: A Small-Cap Grocer Still Growing
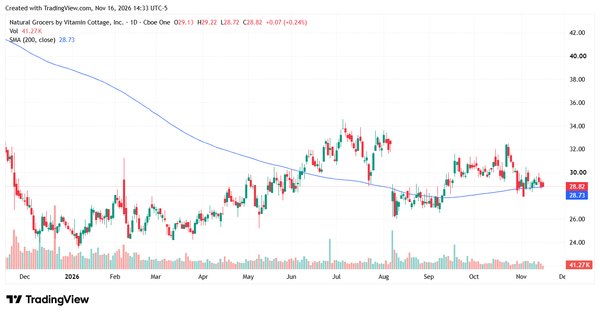
Natural Grocers by Vitamin Cottage (NYSE: NGVC) trades at about 14x earnings. That’s the highest multiple here, but still under 15x earnings. The stock carries a Moderate Buy rating and yields about 2.1%. Its $37.50 price target implies roughly 30% upside.
The company operates 175 stores in 22 states. In its fiscal third quarter, net sales rose 1.8% to $334.7 million. Comparable-store sales grew 1.2%, accelerating from 0.5% in the prior quarter. EPS slipped to $0.48 from $0.50.
Shoppers are visiting slightly less often but spending more per trip. The company’s loyalty program now accounts for 84% of sales. Management is targeting 4% to 5% annual unit growth. The next test comes on Nov. 19, when Natural Grocers reports fiscal fourth-quarter results.
Cheap Consumer Staples Stocks Still Need a Catalyst
A weak 2027 outlook for consumer staples stocks is already reflected in many share prices. That’s what makes this group interesting. Each of these five trades under 15x earnings, yet each has a driver the market may be underweighting. For The Andersons and Darling, it’s earnings power and cash generation. For Herbalife and Natural Grocers, it’s steady sales growth. For John B. Sanfilippo, it’s recovery from a bad quarter. None is risk-free. But when sentiment is this poor, these stocks don’t need perfection. They only need to beat low expectations.
Leave a Reply